On September 30, we hosted our annual private investor event at The Hazelton in Yorkville. The evening brought together the investors behind Morrison Financial’s mortgage income funds and a panel of experts who specialize in the Ontario real estate market - a data platform founder, a capital markets banker, and a land use planner.The conversation was about where the market goes from here: what gets built, what gets financed, and what that means for anyone participating in Ontario real estate.
David Morrison, President and Chief Executive Officer, opened the evening by thanking the investors who have placed their trust in the firm, and by going back to where it started.
David founded Morrison Financial in 1987 after beginning his career as a lawyer, with a simple idea: provide tailored asset-based financing to businesses that the banks were not set up to serve. Since then the firm has arranged more than $1.7 billion in financing across private and institutional capital, making it one of Canada’s longest-standing non-bank lenders.
Morrison Financial has lent through the early-1990s correction, the 2008 credit crisis, and across interest rate cycles. The firm has refined its lending discipline focusing on short-term construction, development and bridge mortgages secured by real estate in Ontario’s major markets, plus condominium corporation financing for capital repairs and reserve fund shortfalls.
Matthew Solda, MBA, Senior Vice President at Morrison Financial, moderated a conversation with three panelists who each see a different slice of the same market: Hanif Bayat, Ph.D., Founder and CEO of WOWA.ca, which aggregates market and economic data across more than a hundred Canadian financial institutions and lenders; Jeff Wagner, Senior Managing Director, Capital Markets at Marcus & Millichap Capital Corporation, who places debt and equity on commercial real estate transactions; and Paul Demczak, Principal at Batory Urban Planning & Project Management, who works on the approvals side where projects either become viable or do not.
The panel began from a position that surprises people. There is no shortage of capital; the constraint is where it is willing to go.
The major banks are carrying large balance sheets and residential secured lending portfolios that have continued to grow. Their loss experience on those books remains very low. What has changed is appetite. Several banks and credit unions have stepped back from the construction and land lending they used to do and shifted toward CMHC-insured product. In some cases they are over-allocated to land with no clear repayment timing, and have simply paused.
That is the gap private lending exists to fill. The banks have excellent takeout financing, but their products do not adapt quickly to changing market conditions - and the infill construction space is exactly where that rigidity shows. A private lender that can underwrite a site-specific deal in weeks is not competing with a bank for the same loan; it is financing the opportunities the bank will not.
The panel’s working assumption was that this does not last indefinitely. Lenders have to lend. As condominium projects complete and repay, allocation frees up and the banks come back - but on their own timeline, not the market’s.
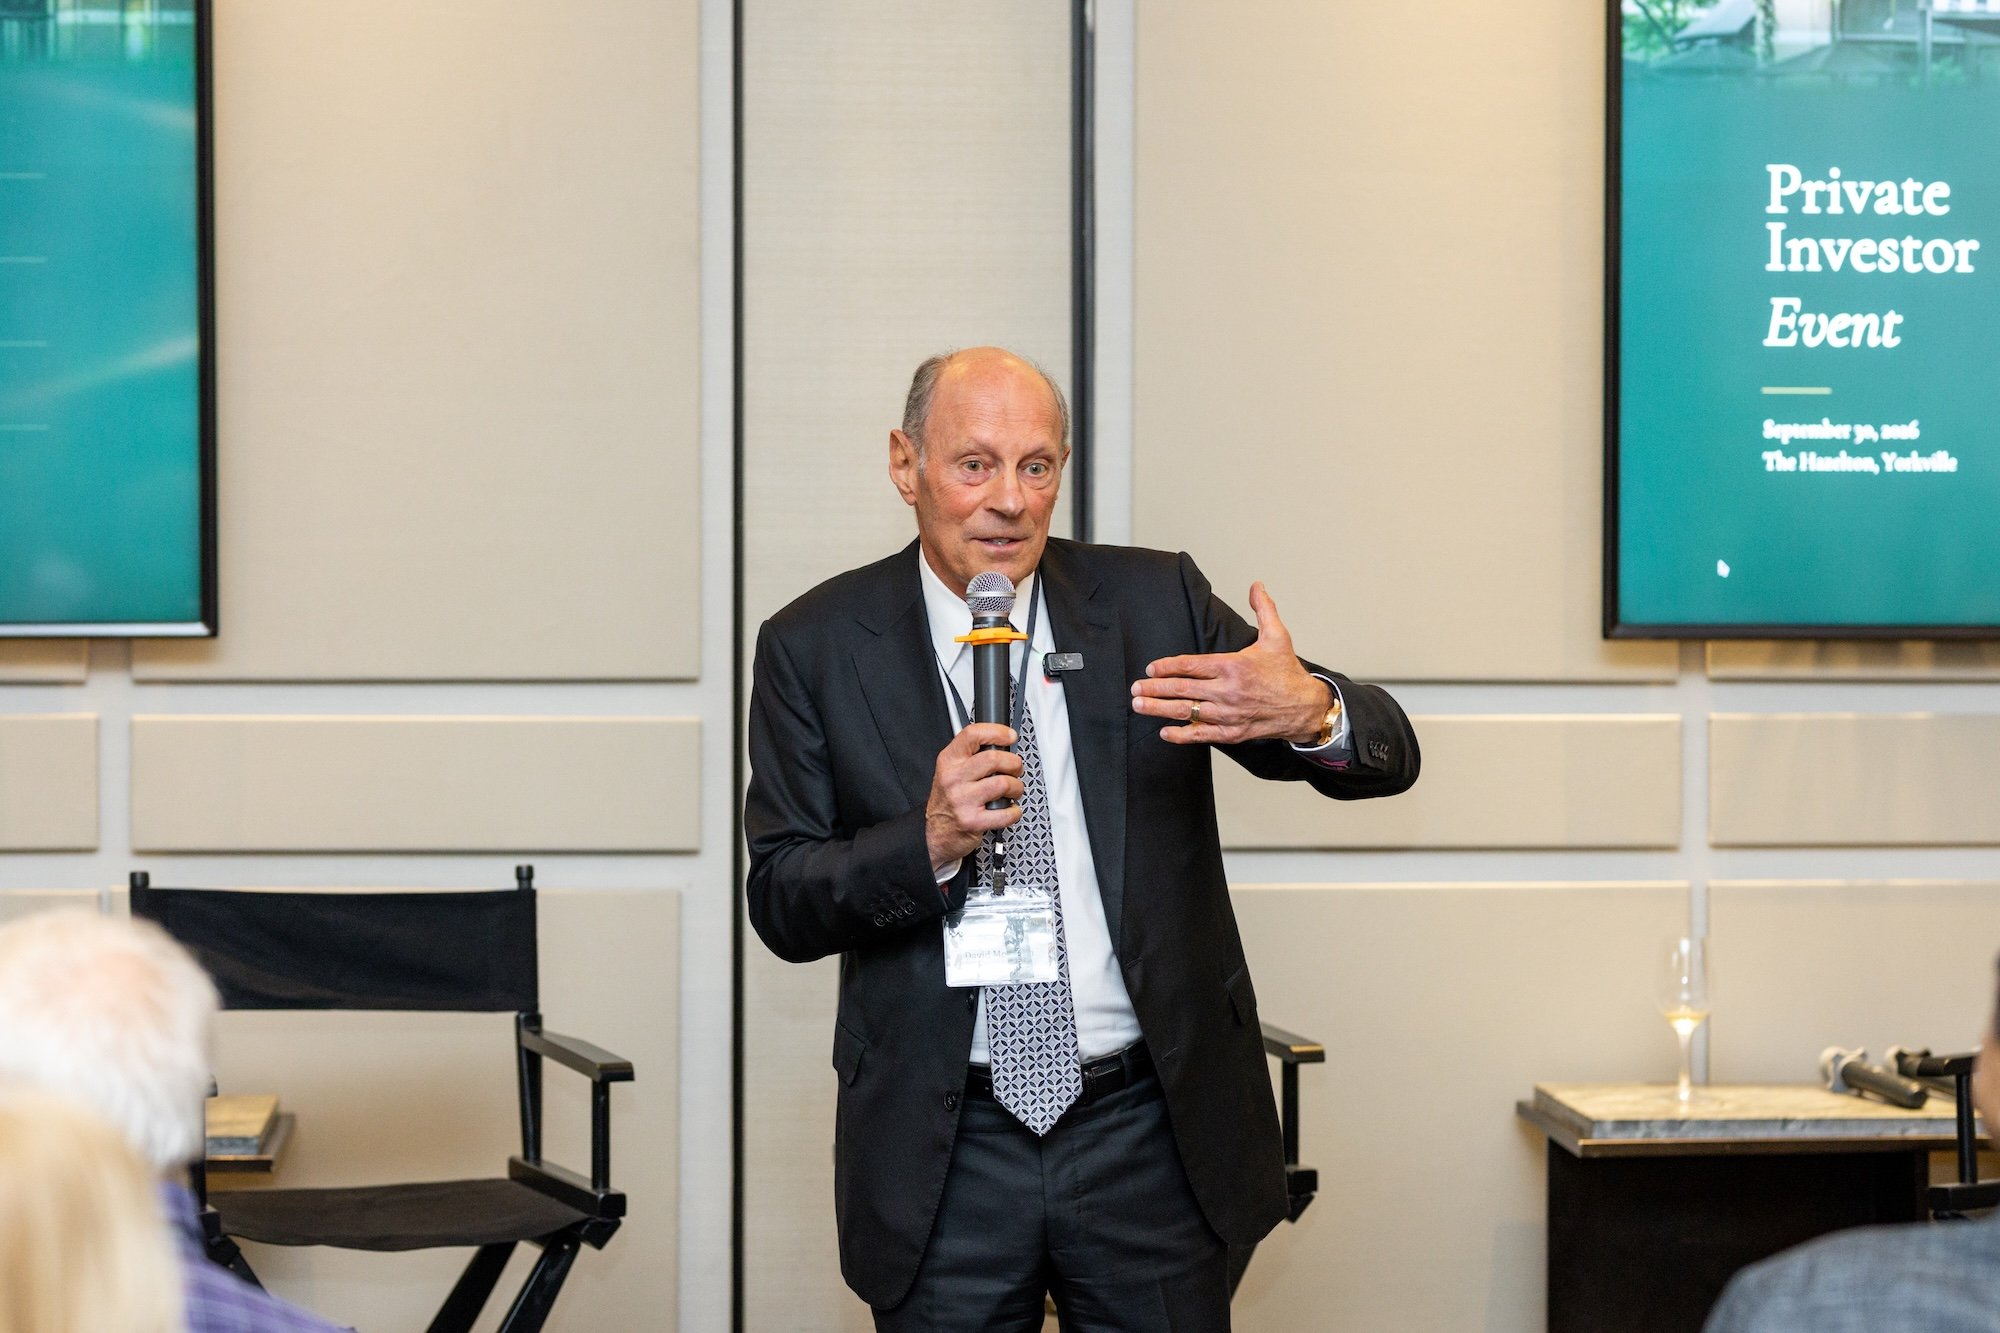
David Morrison opened the evening by thanking the investors at the event.
There is a widespread impression that rates have moved dramatically. Over the past 18 months to two years, they have been relatively stable. What has moved is volatility, and volatility is what creates uncertainty in underwriting, not the level itself.
More recently, mortgage rates have begun ticking up - modestly, in the range of 20 to 30 basis points - after bond markets had been signalling it for months. The expectation discussed was a further increase over the coming year rather than the cuts many borrowers were waiting for.
A useful correction came early in the discussion. There is no single Canadian real estate market. Southern Ontario is under pressure. Quebec is hot. Alberta is stable. And within Southern Ontario the divergence continues. Toronto has seen price declines over the past year; Kitchener-Waterloo and Cambridge have been roughly flat. Outside the GTA, where affordability is better and the Toronto cost structure does not apply, low-rise product is still being absorbed - Cambridge, Kitchener-Waterloo, Barrie, Stratford. Family-sized units, townhouses, surface parking, light amenities.
The pivot everyone on the panel is seeing: condominium sites converting to purpose-built rental, driven by the absorption problem in the condo market, with CMHC-supported takeouts defining the exit. And a broader shift toward low-rise and infill, where absorption is better and both equity and lender demand follow.
This matters to a lender more than it might appear. What makes early-stage construction lending work is a credible exit - a takeout that will be there when the loan matures - and the pivot is what is creating those exits.
The panel did not reach consensus on this point.
The planning view: zoning remains a real constraint, and the complexity is the problem as much as the restriction. Municipal bylaws set site-specific parameters - setbacks, floor plates, minimum and maximum heights - so a developer who wants to make a building shorter and more efficient has to reopen the zoning bylaw and run the entire approval process again. Down-zoning is now a meaningful share of planning work, particularly in secondary markets where municipalities pushed for density the site could not actually support. One such re-approval was described as having cost three years.
The capital markets view: there is no zoning shortage. Large builders are sitting on entitled density they have no idea what to do with. The binding constraints are servicing and affordability.
Both views had evidence behind them, and the servicing point was the one everyone agreed on. Kitchener’s water allocation restriction held up projects publicly. In South Oakville, the Navy Street pumping station upgrades required for additional density are still years out. A site with existing servicing allocation has a structural advantage over an otherwise identical site that has to wait.
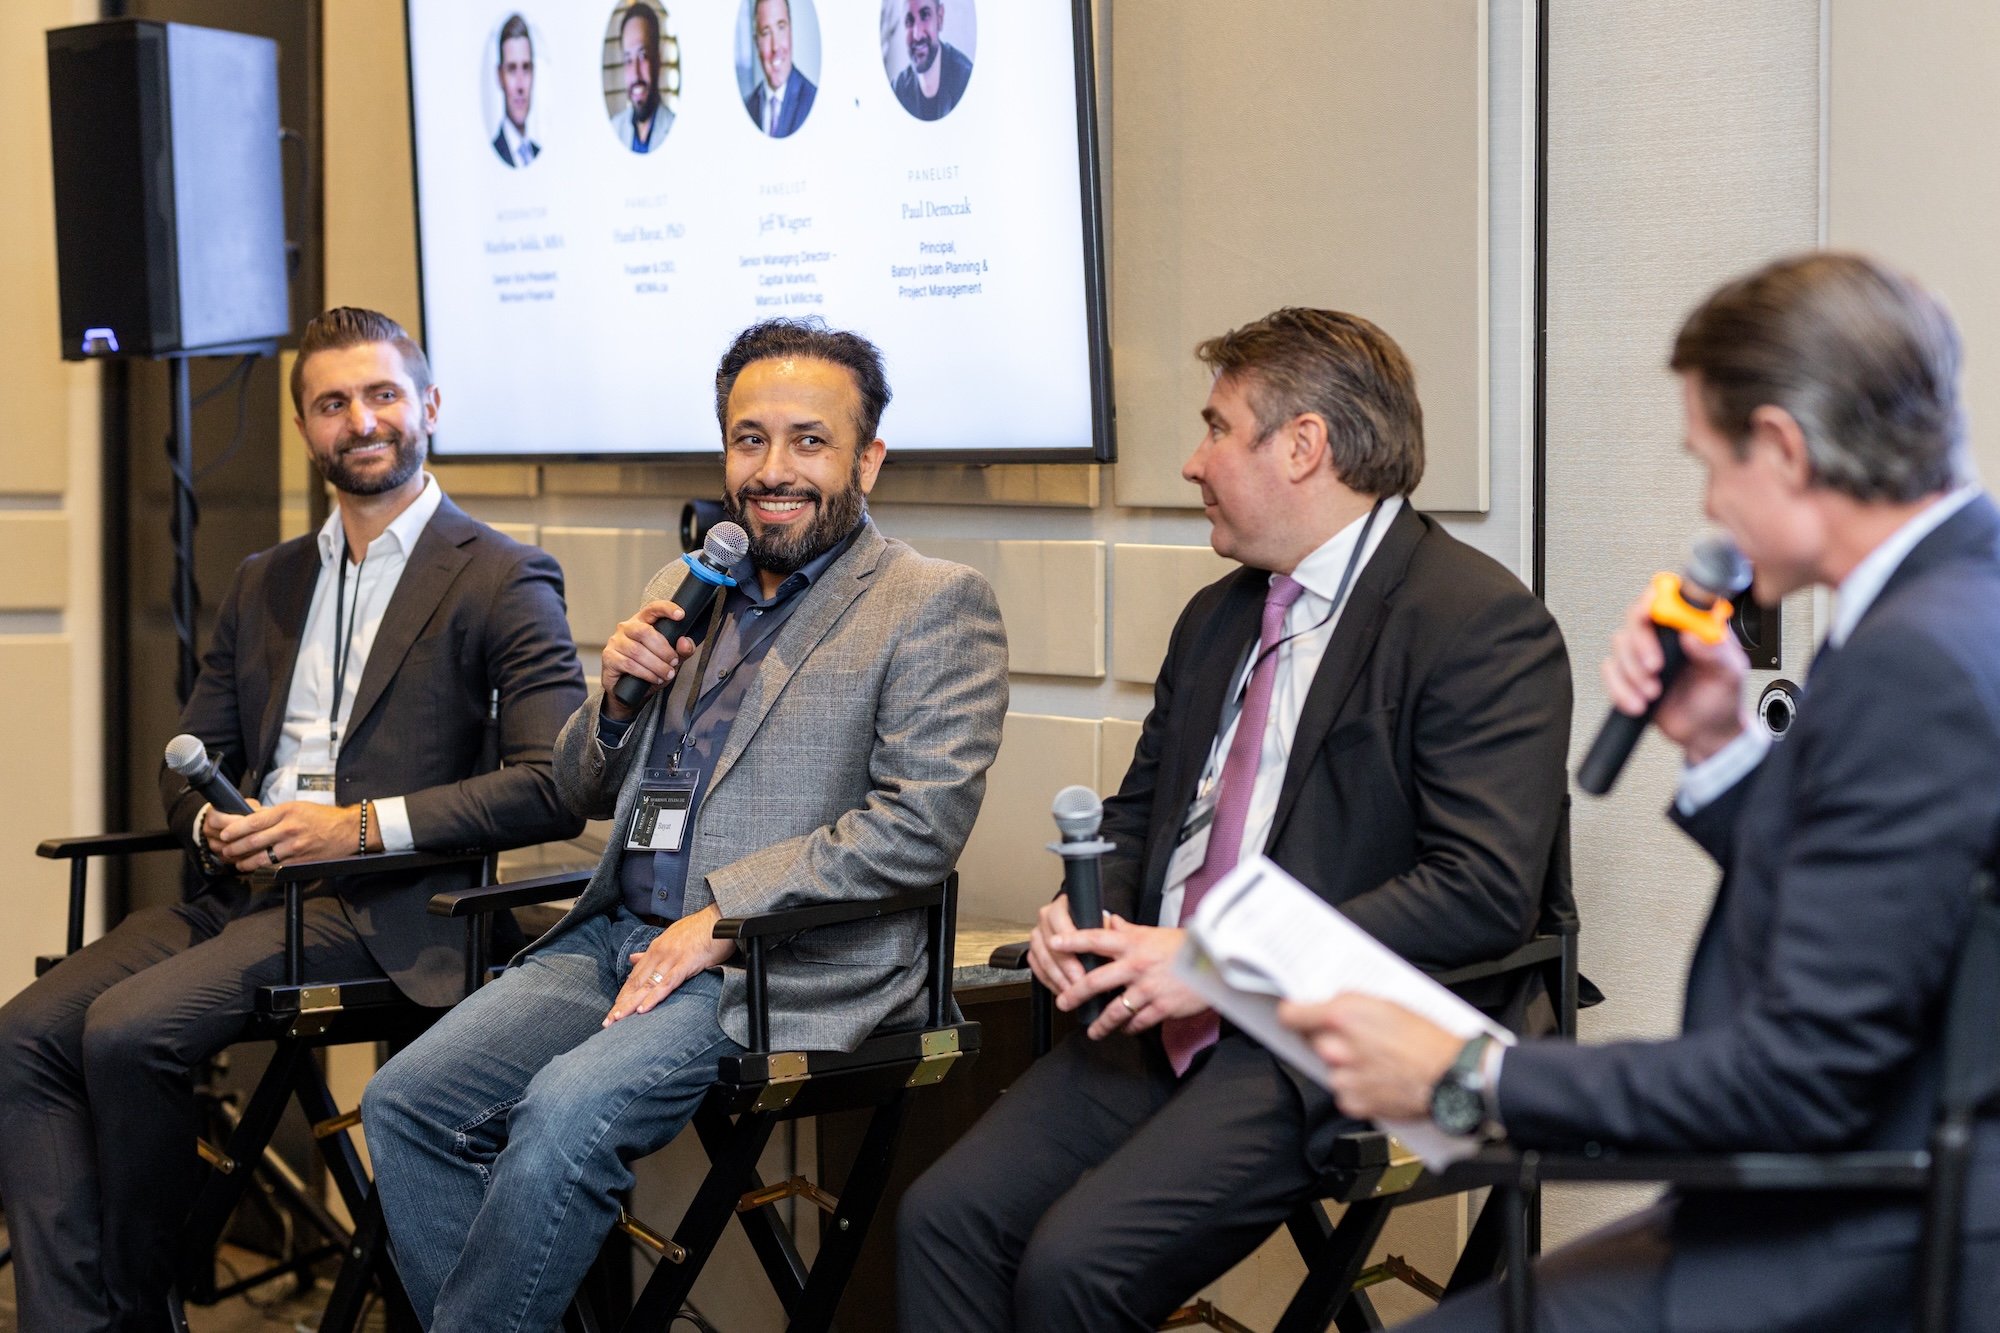
Expert panel for the evening. From left to right: Paul Demczak, Hanif Bayat, Jeff Wagner, Matthew Solda
For roughly a decade, policy moved in the direction of making development harder. That has reversed. Development charge deferrals and relief, HST changes, and as-of-right permissions have moved some projects from not viable to marginally viable.
Developers are actively designing around these frameworks. Buildings are being right-sized to fit DC relief thresholds, then expanded afterward so only the incremental charge is payable - savings in the hundreds of thousands of dollars on a single project. Municipalities are competing with incentives: downtown Oshawa offering zero development charges, no cash-in-lieu of parkland, and ten-year tax increment financing; affordable housing grants in North Oakville.
The consensus was that this has helped but has not gone far enough, and that development charges remain at the top of the list of what makes housing unaffordable. Municipalities became dependent on that revenue during the boom and have not found a politically acceptable way to replace it.
If housing starts are not happening now, and it takes three to five years or more to take a development from start to completion, then today’s weak start volumes become a shortage of new product several years out. The pipeline currently coming online thins by 2028. Meanwhile the demand side is uncertain - population growth has been flat, and developers are reluctant to commit without knowing who will buy or rent the finished product. That ambiguity is itself a constraint on starts, which reinforces the gap.
The reason we host this event is that our investors are exposed to exactly the market the panel was discussing. Every mortgage in the portfolio is secured by Ontario real estate, so approval timelines, construction costs and the availability of takeout financing are the key inputs to how our loans perform.
Morrison Financial launched its Senior and Junior Mortgage Income Funds in 2020 to give investors access to the same mortgage portfolio the firm has been building since 1987. Both are open-ended mutual fund trusts investing in a diversified pool of short-term construction, development and bridge mortgages secured by real estate in Ontario’s key metropolitan markets.
The two funds share one underlying mortgage pool and differ in where they sit in the capital stack:
- The Senior Fund holds the priority position on loan proceeds, which gives it the lower risk profile of the two.
- The Junior Fund sits behind it and takes the first loss, which is what creates the Senior Fund’s protection - and what accounts for its higher target return.
As an alternative investment, a mortgage investment fund of this kind occupies a position most portfolios do not otherwise reach. It is not a GIC and it is not a bond fund. Distributions are monthly, the security is a registered mortgage on real property, duration is short relative to most private credit, and capital preservation rather than yield is the primary credit consideration in every loan the team underwrites.
None of what the panel described is comfortable. But it is worth being precise about what it is: a market where capital has become selective, where exits have to be proven rather than assumed, and where the projects that get built are the ones that were underwritten properly in the first place. For a lender with capital to deploy and no obligation to deploy it quickly, that is a more workable environment than one in which everything funds easily and margins compress.
Morrison Financial has lent through various market cycles. They looked different from one another but they rewarded the same things: conservative loan-to-value, real sponsor equity, security on hard assets in markets where the product actually sells, and the discipline to decline a deal that does not clear the bar.
Our read going into 2027 was not changed by the evening so much as reinforced by it. Fewer projects will start. The ones that do will need tailored financing structure rather than a bank’s product sheet. Takeouts will matter more than they did five years ago, and additional considerations like service allocation will separate sites that look identical on paper.
We also do not form that view on our own. Hanif, Jeff, and Paul each see a part of this market that we do not, and their insights are much appreciated by our team. Our thanks to them, and to the investors who joined us at The Hazelton.
Morrison Financial’s Senior and Junior Mortgage Income Funds are offered to qualified investors through Belco Private Capital Inc., our exempt market dealer. To receive the Offering Memorandum and current fund materials, contact Tarik Ansara ([email protected]).
Disclosure: This post is for information purposes only and does not constitute an offer to sell or a solicitation to buy securities. Units of the Morrison Financial Mortgage Income Senior Fund and the Morrison Financial Mortgage Income Junior Fund are offered only to qualifying investors pursuant to available prospectus exemptions and only through a registered dealer. Prospective investors should read the Offering Memorandum, including the risk factors, before investing. Past performance is not indicative of future results. Views expressed by panelists are their own and do not represent the views of Morrison Financial. Morrison Financial Mortgage Corporation is licensed as a mortgage brokerage in Ontario (FSRA Brokerage Licence No. 10047).