For many Canadians, an RRSP is little more than an annual line item, a retirement account where contributions disappear each year into a standard mix of mutual funds chosen at a bank branch years ago. While that set-it-and-forget-it approach has been the default for decades, it has also left many investors with portfolios they haven’t critically reviewed in a generation.
The more pressing question, especially for those approaching or already in retirement, isn’t whether to contribute. It is what that money is actually doing inside the account. The range of assets an RRSP can legally hold is far wider than most realize, and private mortgage funds remain one of the most overlooked alternatives available to retail investors. For investors seeking predictable income and true diversification away from public market volatility, understanding how this asset class fits into a registered plan is a valuable exercise.
Here is how the mechanism works and where private mortgage funds fit into a well-rounded retirement strategy.
An RRSP Is a Container, Not an Investment
To understand the flexibility of the plan, it helps to clear up a common misconception: an RRSP (Registered Retirement Savings Plan) is not an investment product itself. Introduced by the Canadian government in 1957 and governed by the Income Tax Act, it is simply a tax-sheltered container. It offers two primary benefits: a tax deduction on your contributions and tax-deferred growth on whatever you choose to hold inside.
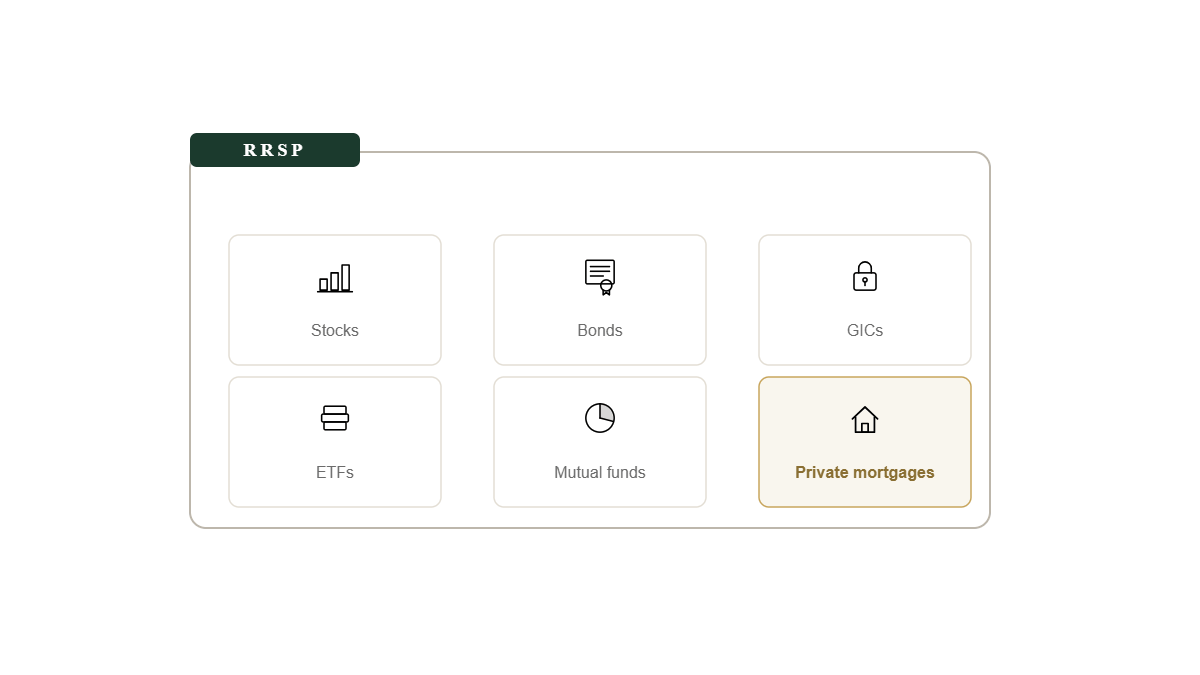
People often say, “I’m invested in an RRSP.” More accurately, you invest through your RRSP. Whether you fill that container with stocks, bonds, GICs, mutual funds, ETFs, or qualified private assets is entirely up to you. This choice explains why two investors making identical contributions for decades can end up with vastly different retirement balances.
How Tax-Deferred Growth Works
The real power of an RRSP lies in uninterrupted compounding. Inside the plan, investment gains do not trigger an annual tax bill from the Canada Revenue Agency (CRA); interest, dividends, and capital gains compound fully over time.
For illustrative purposes only, if you put $25,000 into an RRSP and it grows to $62,500 over fifteen years, you owe zero tax on that $37,500 of growth during the holding period. In a non-registered account, that same growth would be chipped away by annual taxes, leaving less capital behind to compound.

Tax is deferred until you withdraw the funds. For most Canadians, this happens in retirement when their overall income, and consequently their marginal tax bracket, is lower. Furthermore, because contributions reduce your taxable income in the year they are made, they often generate a tax refund. Reinvesting that refund further accelerates your long-term growth.
However, tax-deferred does not mean tax-free. Every dollar withdrawn from an RRSP is taxed as ordinary income. Additionally, by December 31 of the year you turn 71, the account must be converted into a Registered Retirement Income Fund (RRIF), triggering mandatory minimum annual withdrawals. Keeping this lifecycle in mind is essential when selecting the right assets for your portfolio. This is one reason interest-yielding assets are particularly well-suited to registered plans: outside of a registered account, interest income is taxed as ordinary income, while dividends and capital gains generally receive more favourable tax treatment. Sheltering interest income inside an RRSP therefore captures a meaningful tax efficiency that other asset classes already enjoy in non-registered accounts.
Contribution Limits and the First 60 Days
Your RRSP contribution room is set each year based on 18% of your earned income from the prior year, up to an annual dollar maximum. For the 2025 tax year, the maximum was $32,490. For 2026, it’s $33,810. Your personal limit appears on your most recent Notice of Assessment from the Canada Revenue Agency, or in your CRA My Account.
Unused contribution room carries forward indefinitely, which is helpful. The years of tax-deferred compounding don’t, which is less helpful. A $25,000 contribution today has decades more time to grow than the same $25,000 contributed five years from now.
Contributions made in the first 60 days of the following calendar year (typically January 1 through the end of February or early March) can be designated against either the prior tax year or the current one. That’s why late February is consistently the busiest stretch of the RRSP year, as investors finalize their previous year’s tax position. The CRA allows a $2,000 lifetime over-contribution buffer without penalty, but any excess beyond that triggers a 1% monthly penalty on the overage until it’s corrected.
Three Common Misconceptions About RRSPs
Contributions are tax-free. They are tax-deferred. Aside from specific provisions like the Home Buyers’ Plan or the Lifelong Learning Plan, every dollar that eventually leaves your RRSP is taxed as income in the year of withdrawal. The benefit is the decades of undiminished compounding, not tax avoidance.
An RRSP can only hold bank products. Many Canadians associate RRSPs strictly with mutual funds or GICs because that is what they were offered when opening their first account. In reality, the plan can hold a vast array of qualified investments, including private market securities.
Private investments are ineligible. The Income Tax Act, together with section 4900 of the Income Tax Regulations, explicitly outlines what qualifies as an eligible investment. Certain private asset structures, including qualifying private mortgage funds, meet these criteria when held through an approved trustee.

What an RRSP Can Hold
Beyond standard mutual funds, an RRSP can hold:
- Publicly traded Canadian and foreign stocks
- Government and corporate bonds
- Guaranteed Investment Certificates (GICs)
- Exchange-traded funds (ETFs)
- Cash and cash equivalents
- Certain qualified private investments, including qualifying private mortgage funds and shares of certain Mortgage Investment Corporations (MICs), held through an approved trustee
Most investors miss this last category simply because of retail banking setups. Major banks naturally prioritize their own in-house products. To hold private securities, you need a Self-Directed RRSP with a specialized trustee equipped to handle them. For investors who have built meaningful capital over the years and want to diversify away from traditional equity markets, this is where the conversation usually shifts from “how much to save” to “how to allocate”.
How Private Mortgage Funds Work
A private mortgage fund is a pooled investment vehicle that originates and holds a diversified portfolio of mortgage loans secured by Canadian real estate. The fund raises capital from investors, deploys it as loans to vetted borrowers, and distributes the resulting interest income back to investors on a regular schedule. The underlying loans are typically issued outside the traditional institutional banking system to real estate developers, builders, or commercial asset owners who need nimble financing that conventional banks struggle to process quickly. Whether they require capital for early-stage development, land acquisition, or short-term bridge financing, they turn to alternative lenders for speed and flexibility.
For individual investors, a fund structure is the most practical way to access this asset class. Rather than holding a single mortgage, investors gain exposure to a diversified book of loans through their fund units, which spreads borrower-specific risk across the portfolio. The fund manager handles sourcing, underwriting, origination, portfolio monitoring, and any necessary workout or recovery activity. Eligibility for any specific private mortgage product depends on its legal structure (trust units, limited partnership units, or MIC shares) and whether it satisfies the qualified investment rules under the Income Tax Act. Investors should also be aware of the “connected person” and prohibited investment rules in section 207.01, which can disqualify an otherwise eligible holding if the RRSP annuitant has a close relationship to the borrower or holds a 10%-or-greater interest in the issuer.

Why Private Mortgage Funds Appeal to RRSP Investors:
Income over appreciation. Unlike equity real estate investments where returns depend on property values rising over time, a private mortgage fund generates returns for investors through the contractual interest payments on the loans it holds. This provides a predictable income stream, which is highly valuable for investors prioritizing capital preservation.
Asset-backed security. Every loan in a well-managed fund is secured by real property. If a borrower defaults, the fund has a legal mechanism to recover capital through the underlying real estate. While no investment is entirely risk-free, this asset-backed structure offers a fundamentally different risk profile than equity.
Low market correlation. Returns are driven by loan terms and credit performance within the fund, not the daily emotional swings of the stock market. Adding a private mortgage fund allocation can help anchor an RRSP portfolio, reducing overall volatility without forcing you to sacrifice yield.
How We Work at Morrison Financial
We have operated in Canada’s private financing market since 1987, underwriting construction, development, and bridge financing to strict institutional standards. When developers need capital secured against land or future builds, we structure the financing at an agreed rate. For our investors, this translates into consistent interest income backed by Canadian real estate. Investor access to this asset class is provided through our Mortgage Income Funds, the Senior Mortgage Income Fund (Senior Fund) and the Junior Mortgage Income Fund (Junior Fund), which pool investor capital into diversified portfolios of Morrison-originated mortgage loans. The Funds have produced consistent returns for investors since inception. As of the month ending May 2026, the Funds’ effective annual returns were 6.75% and 8.75% for the Senior Fund and Junior Fund, respectively.

Both funds are distributed through Belco Private Capital, our exempt market dealer partner, and are structured to be held inside RRSPs, RRIFs, TFSAs, and other registered plans where eligible. Because we manage a single, diversified mortgage portfolio, you can easily tailor the investment to match your specific financial stage:
Cash Distribution Option (Without DRIP)
- Goal: Regular cash flow.
- How it works: The interest income generated by the mortgage portfolio is distributed directly into your RRSP account on a monthly or quarterly schedule.
- Who it suits: Investors who are approaching or currently in retirement and need a steady, predictable income stream to supplement their lifestyle or meet mandatory RRIF withdrawal requirements.
Capital Growth Option (With DRIP)
- Goal: Long-term capital accumulation.
- How it works: By enrolling in our Dividend Reinvestment Plan (DRIP), your distributions are automatically reinvested back into the fund to purchase additional units, compounding your principal without manual intervention.
- Who it suits: Investors with a longer time horizon who do not need immediate cash flow and want to maximize the compounding power of tax-deferred growth inside their RRSP.

Funding RRIF Minimums Without Selling Into a Downturn
Once an RRSP converts to a RRIF, mandatory minimum withdrawals begin. For investors whose retirement assets are concentrated in equities, those minimums can force the sale of fund units during a market decline, locking in losses at the worst possible time. This is the practical version of what advisors call sequence-of-returns risk. A monthly-distribution private mortgage allocation inside the RRIF can fund some or all of the required minimum directly from interest income, allowing the equity portion of the portfolio to recover without being drawn down for cash flow. This is one of the more compelling, and frequently overlooked, reasons to consider a contractual-income allocation alongside traditional equity holdings as retirement approaches.
Factors to Think Through
While private mortgage funds offer an excellent alternative to standard bank products, they are sophisticated instruments that come with specific parameters:
Investor Qualification: Under Canadian securities regulations (National Instrument 45-106), private investments are generally available to accredited or eligible investors who meet specific income or net worth thresholds. Our minimum investment starts at $25,000, and our team walks you through the qualification process before any account is opened.
Time Horizon and Liquidity: Private mortgage funds have longer holding periods and more limited liquidity than publicly traded equities. Redemptions require specific notice periods detailed in the fund’s offering documents. This makes them an excellent fit for long-term retirement capital, but unsuitable for emergency funds you might need at a moment’s notice.
Due Diligence: Every private asset is accompanied by an Offering Memorandum. It is important to review these documents, ideally alongside a qualified advisor, to understand the fund’s specific lending criteria, fee structures, and default management protocols.
Questions Sophisticated Investors Should Ask
Beyond the standard suitability questions, investors evaluating a private mortgage fund should also ask:
How does the manager underwrite new loans, and what loan-to-value discipline applies?
Consistent LTV ceilings, independent appraisals, and documented underwriting criteria are the foundation of a credible private mortgage portfolio.
How are borrower defaults handled, and what is the recovery process?
A manager should be able to walk through specific recovery mechanisms, typical workout timelines, and historical loss experience.
What is the manager’s track record? Has distributions or redemption been paused before?
A strong manager should be able to weather through different market cycles to generate consistent returns for its investors.
Reviewing What's Inside
An RRSP is one of the most effective financial tools available to Canadians, and its contents will ultimately shape what your retirement looks like. Re-evaluating your holdings and looking beyond traditional bank offerings is an incredibly worthwhile exercise, especially as you pivot from aggressive growth toward income and capital preservation.
If you would like to explore how a private mortgage fund allocation aligns with your RRSP strategy, Morrison Financial can walk you through the setup, eligibility, and distribution options that best serve your goals.
Frequently Asked Questions
Can I invest in a private mortgage fund through my RRSP?
Yes, where the fund is structured to satisfy the qualified investment rules. Most individual investors access this asset class through a pooled fund (such as a Mortgage Investment Corporation, trust, or limited partnership) rather than holding a single mortgage directly, because the fund vehicle provides diversification, professional underwriting, and registered-plan eligibility in a single product.
What is a self-directed RRSP?
A self-directed RRSP is an account administered by a trustee that allows the holder to choose from a broader range of qualified investments than a typical bank-branch RRSP, including certain private securities. The trustee handles custody, tax reporting, and regulatory compliance.
What happens to my RRSP at age 71?
By December 31 of the year you turn 71, your RRSP must be converted into a RRIF, used to purchase an annuity, or withdrawn as a lump sum. A RRIF triggers mandatory minimum annual withdrawals that scale upward each year and are taxed as ordinary income.
What is the minimum investment for a private mortgage fund?
Minimums vary by manager and by the investor's qualification under National Instrument 45-106. At Morrison Financial, the minimum starts at $25,000 for eligible investors. Specific minimums and qualification requirements are set out in the offering documents for each fund.
This article is for informational purposes only and does not constitute tax, legal, or investment advice. Eligibility for private investments is determined under applicable securities legislation. Please review all offering documents and consult a qualified professional before making any investment decision.
Sources
This article draws on publicly available information from the following primary sources:
Canada Revenue Agency (CRA). RRSP rules, contribution limits for the 2025 and 2026 tax years, the 60-day contribution window, over-contribution buffer and penalty rates, conversion to a RRIF at age 71, Home Buyers’ Plan, and Lifelong Learning Plan. canada.ca
Income Tax Act of Canada (R.S.C., 1985, c. 1). Sections governing registered retirement savings plans, qualified investments that can be held inside an RRSP, and over-contribution penalties.
Canadian Securities Administrators (CSA), National Instrument 45-106, “Prospectus Exemptions”. Definitions of “accredited investor” and “eligible investor” categories used in private investment offerings.